Pridobite najnovejše informacije iz trga emisijskih kuponov in se prijavite na brezplačno tedensko prejemanje novic


This newsletter was published 17.11.2026 at 17:12 pm CEST
The current prices on the European carbon market are as follows:
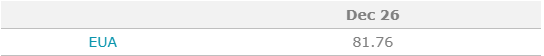
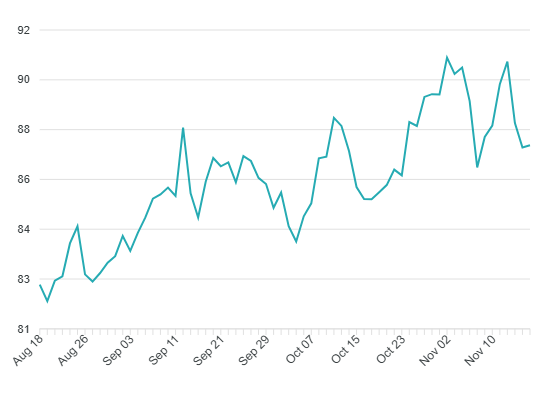
December-26 EUAs came under heavy selling pressure, with prices dropping more than 5 EUR intraday in their sharpest decline since early February. The move took the market below 82 EUR per tonne its lowest level in three months, with very little support emerging along the way. Several moving averages were breached with ease, while 85 EUR was the only level that initially managed to attract some buying interest. What makes the sell-off particularly difficult to explain is the lack of any clear news or fundamental catalyst that would justify such an abrupt repricing, at least for now. Market participants have pointed to several possible explanations, including somewhat bearish short-term weather forecasts and deteriorating technical signals. The latest CoT report has also come under scrutiny, showing investment funds increasing their net long exposure by 5.8 million tonnes week on week. By the end of last week, aggregate fund positioning was approaching 50 million tonnes, leaving the market relatively crowded on the long side. This may have triggered systematic profit-taking, while the initial decline could also have activated some stop orders, accelerating the downward move. Perhaps the most striking feature of today’s session was the sheer amount of trading activity. More than 40 million allowances changed hands on screen alone, marking the highest daily volume in six months. This is roughly twice the average daily volume recorded between April and November, highlighting the scale of the repositioning and liquidation taking place. Looking ahead, volatility could remain elevated in the coming weeks. December options expiry is now only a month away, with substantial open interest concentrated around several key round-number strikes. Against the backdrop of the recent sell-off and potentially crowded positioning, options-related flows could amplify price movements in either direction.
German power prices are up by 6.80 EUR since last week, with the front-year contract trading at 138.80 EUR/MWh. API2 coal prices are down by 5.25 USD since last week, with the Cal-27 contract trading at 121.75 USD/tonne. Front-year gas prices are down by 3.165 EUR since last week, with the TTF Cal-26 trading at 65.935 EUR/MWh. EUR/USD is down by 130 points since last week and is currently trading at 1.0960.