Pridobite najnovejše informacije iz trga emisijskih kuponov in se prijavite na brezplačno tedensko prejemanje novic


This newsletter was published 30.9.2026 at 16:33 pm CEST
The current prices on the European carbon market are as follows:
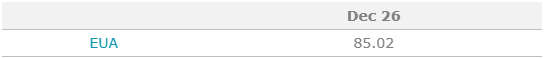
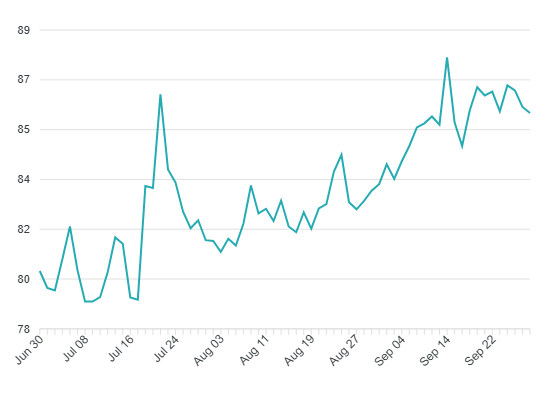
December-26 EUAs moved lower this week after another failed attempt to establish a foothold above 87 EUR per EUA. The market is now trading a tad lower, with the correction coming despite a further build-up in speculative positioning. Investment funds increased their net exposure to around 36 million tonnes, while trading activity is also recovering as liquidity gradually improves following the quarterly option expiry. The combination of stronger fund positioning and softer prices points to a market that remains relatively supported, however it is currently struggling to generate enough momentum to challenge the recent highs. Gas prices have nevertheless remained elevated, with October-26 TTF trading at 69.00 EUR/MWh. The decline has eased some immediate scarcity concerns, but European storage levels remain relatively low ahead of the heating season. Underground storages are currently around 70 percent full, compared with a seasonal average of just shy of 90 percent. The carbon market therefore remains caught between weaker short-term emissions fundamentals and a relatively supportive broader balance. Higher speculative exposure and the approach of the compliance period are helping to underpin prices, while softer gas, power and renewable-driven thermal displacement are limiting the upside, at least for now.
German power prices are up by 0.40 EUR since last week, with the front-year contract trading at 127.40 EUR/MWh. API2 coal prices are up by 2.35 USD since last week, with the Cal-27 contract trading at 135.75 USD/tonne. Front-year gas prices are down by 0.805 EUR since last week, with the TTF Cal-26 trading at 56.350 EUR/MWh. EUR/USD is down by 40 points since last week and is currently trading at 1.1360.
Price development of EUA Dec2026 futures contract